UPI for Business: What Finance Teams Should Set Up Before Rolling It Out to Employees
Key Takeaways:
UPI for business payments offers consumer-style convenience, but corporate use requires governance, accountability and control.
A smarter approach when enabling business QR code payment is building spend controls, such as limits, approvals and merchant restrictions.
Done right, every UPI payment gets automatically tied to the right employee, budget, and cost centre, with no manual reconciliation needed.
The key is to define user access, spending limits, approvals, attribution and visibility before enabling UPI for business payments at scale.
According to data published by the National Payments Corporation of India (NPCI), UPI processed 29.8 crore transactions in August 2026 alone.
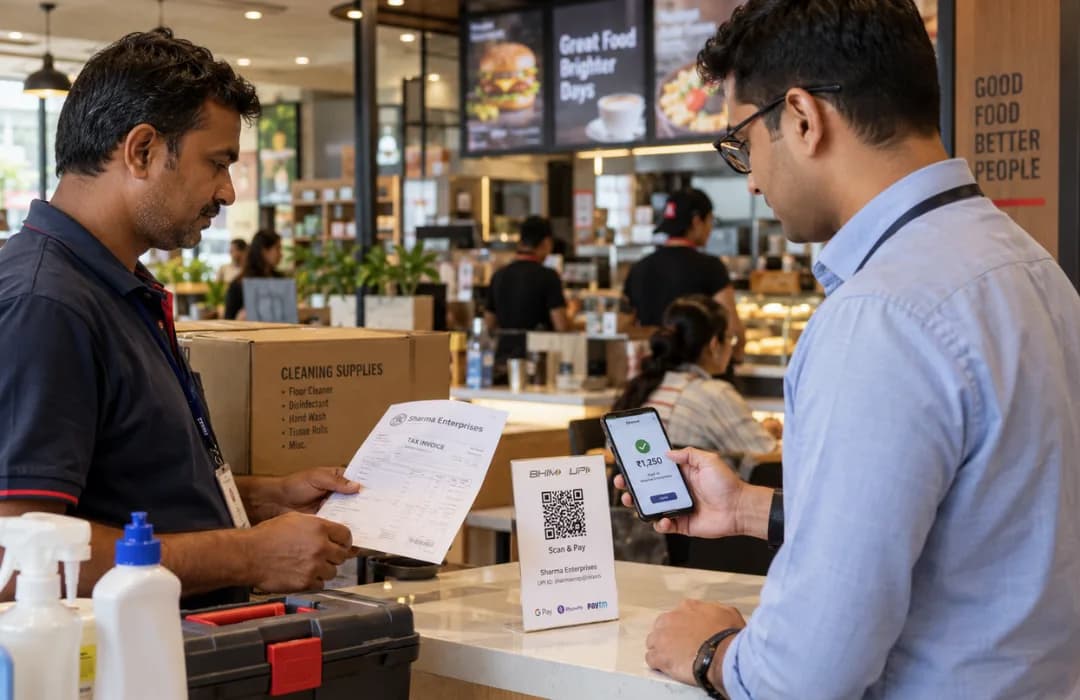
UPI’s payment convenience can also be advantageous for companies. Employees can simply scan a QR code to complete a transaction without carrying cash or using a personal payment method. They may need UPI for legitimate operational expenses, but finance needs the right controls in place before enabling these payments at scale.
Finance must know who is spending, how much they are allowed to spend, where the money is going and which budget or cost centre it should go to. Without these controls, allowing personnel to access UPI just shifts business spending to a faster payment channel without improving transparency.
This is why the issue is not UPI itself, but how enterprises operationalise and govern it. Finance should define the governance framework first, then enable UPI within those boundaries.
Why UPI for Business Payments Needs More Than Access
Consumer payments are designed around convenience. Corporate payments have to balance convenience with accountability, policy enforcement, attribution and visibility. An employee may need to pay a local vendor, make a store-level purchase or handle a recurring operating expense. A QR-based payment can make that transaction quick. But finance needs these requirements to be addressed through defined controls as the payment is made.
Was the employee authorised to spend? Was the amount within the permitted limit? Was the merchant approved? Which department needs to bear the expense? Does the transaction fall within the approved budget? These requirements can be addressed through user authorisation, spending limits, approval workflows, merchant or category restrictions, cost-centre attribution and visibility with audit trails.
So, enterprises must not just focus on allowing or restricting UPI usage. They need to establish the governance framework first so staff can make legitimate company payments within defined policy boundaries.
What Finance Teams Should Set Up Before Rolling Out UPI
Before employees start making business payments through UPI, Finance teams should establish a few basic controls. These controls should be defined before employees are given access.
1. Set Per User and Transaction Limits
Not every employee needs the same spending power. A field employee may need a different limit from a store manager or regional head. Finance teams should ideally set transaction limits based on role, use case or business requirements.
Per-user limits define how much an employee can spend within a specified period, while transaction-level limits define the maximum amount for an individual payment. Both help Finance manage exposure at the user and transaction level.
A different approval or policy threshold can apply based on the transaction value, policy, risk and use case. The objective is to give employees enough flexibility to complete their responsibilities while limiting unnecessary exposure or risk.
2. Define Who Is Authorised to Spend
UPI for business payments should be linked to clearly defined users. Finance teams should establish who can initiate payments, for which purposes and under what conditions. Role-based access can help ensure that payment permissions match an employee’s responsibilities. These permissions should also be updated or revoked when an employee changes roles or leaves the organisation.
When spending rights are assigned at the user level, companies can trace transactions back to the person responsible for them. This also makes it easier to review unusual spending or revoke access when an employee’s role changes.
3. Establish Approval Thresholds
Not all payments require the same level of approval. A practical setup can allow routine, low-value transactions to be made within set limits , while routing higher-value or unusual payments through an approval workflow based on policy and risk. This gives finance the means to continue to oversee transactions without turning every small payment into a manual approval exercise.
4. Enforce Merchant or Spend-Category Controls
Finance heads can also control employee spend by where or what they spend on. For example, enterprises may want to restrict spending to certain merchant types or categories. For instance, a company may restrict payments to approved supplier or expense categories where required by its policy.
This is particularly useful in cases where employees are making frequent operational, branch or site payments. These controls add another layer of protection that extends beyond the transaction amount.
5. Align Spending with Cost Centres and Budgets
A payment shouldn’t end with money leaving the account. The finance team needs to know how to categorise the expense. By linking the transactions to departments, branches, budgets or cost centres, finance can automatically allocate the expense to the appropriate cost centre, department, branch or budget.
Without this attribution, Finance may still have to manually identify where individual transactions need to be recorded.
6. Create Audit Trails and Get Real-Time Visibility
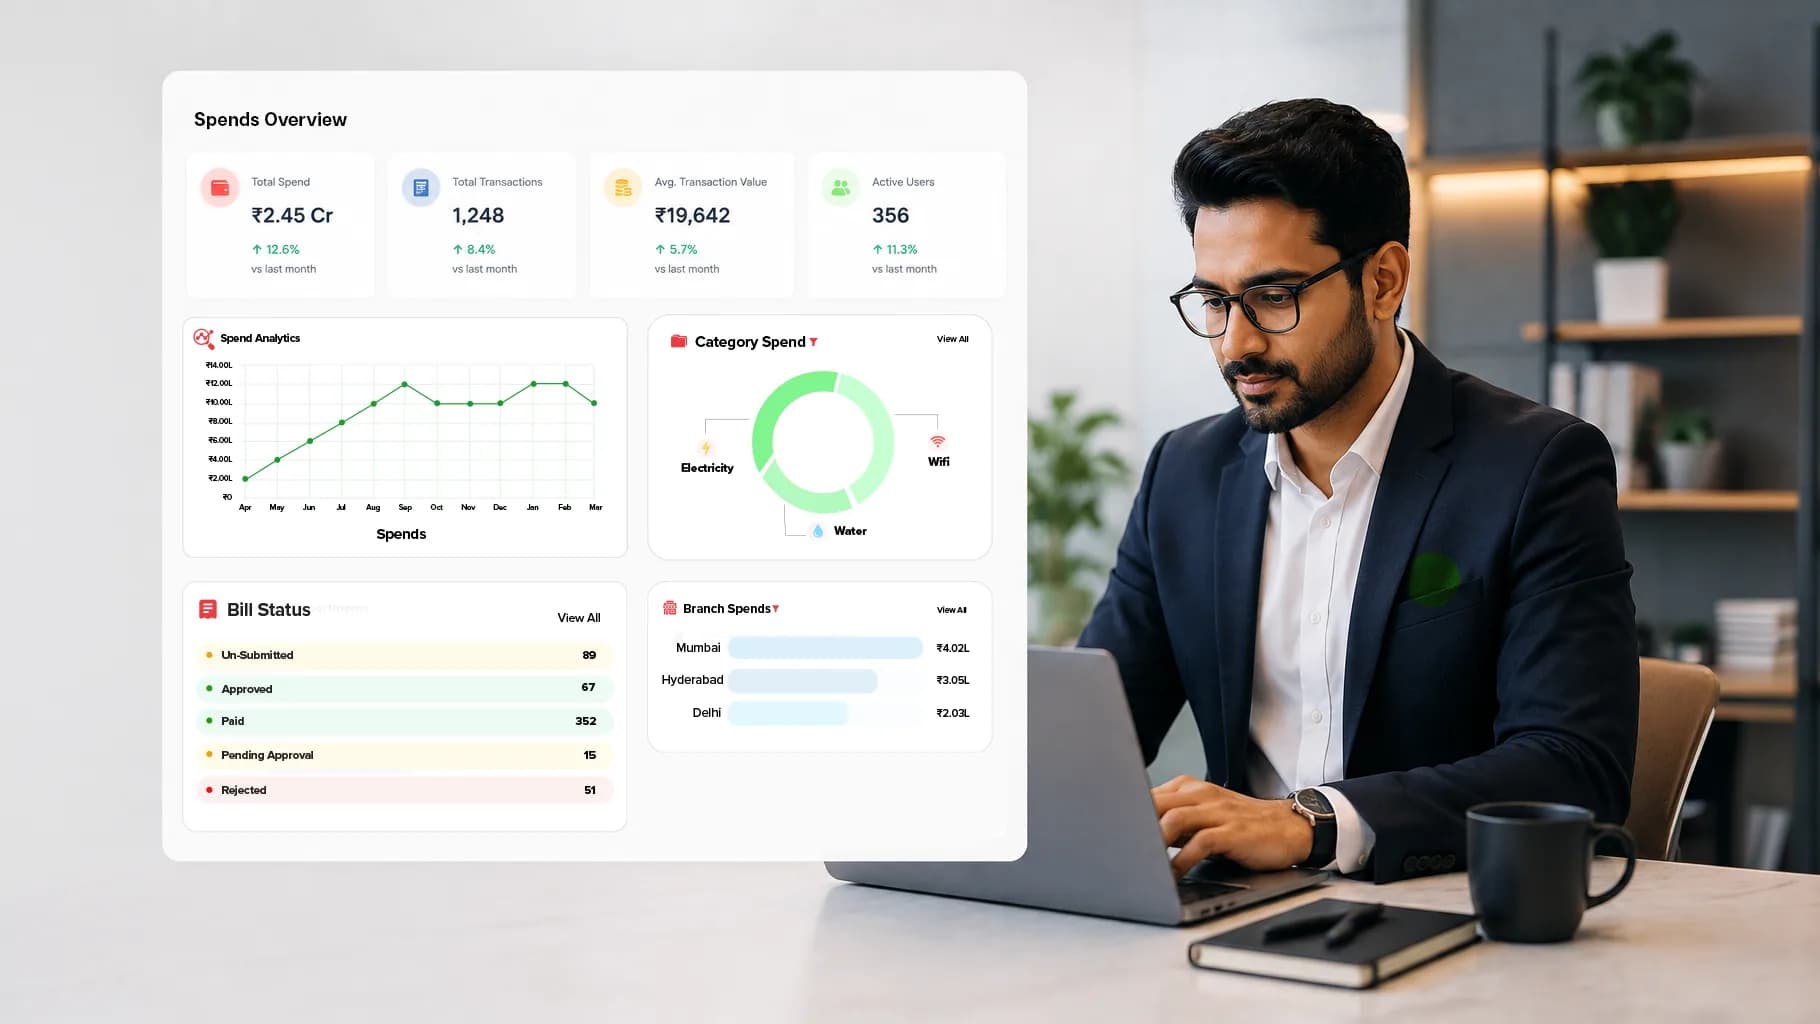
Finance teams need visibility into business spending as it happens. A centralised view can show who made a payment, how much was spent and where the transaction occurred. Audit trails create a record that can be reviewed later.
Together, real-time visibility and audit trails help finance monitor spend, identify exceptions and review transactions without relying on manual reconciliation. This is particularly important if a company has many employees or locations that make small-value payments every day.
How Businesses Can Integrate QR Code Payments with Spend Controls
A business QR code payment doesn’t have to mean giving employees unrestricted access to a payment account. The QR code can simply be the payment interface. The governance layer should determine who can transact, how much they can spend and how the transaction is recorded.
A well-governed flow can look like this:
1. Employee is authorised
2. Spending limit is checked
3. Merchant/payment is checked against the applicable policy or category and routed for approval, where applicable
4. Transaction is recorded
5. Expense is attributed
6. Finance gets visibility
So, the employee gets the convenience of scanning a QR code, while Finance can set spending policies and control expenditures. UPI and QR payments provide the convenience of making the payment, while the spend-management framework provides control, attribution and visibility.
How Zaggle Helps Businesses with UPI-Based Spending
Zaggle’s Business Recurring Expenses solution allows businesses to manage recurring operating costs across branches and locations. With features like UPI spends via the Zaggle App, businesses can facilitate QR-based payments while retaining visibility and control over business spending.
Finance teams can use the solution to control, track and attribute employee- and branch-level spends while enabling UPI-based payments. This makes it possible to implement controls that manage the funding and tracking of business expenses rather than allowing employees to use personal payment methods and reconcile expenses later.
This provides a structured way to combine the convenience of QR-based operational payments with spend visibility, policy controls and accountability for companies with recurring operational costs across multiple locations.
Real Impact: How Subway Simplified Store-Level Payments
Subway, with more than 500 stores across India, provides an example of how these controls can work at scale across multiple locations. Subway used Zaggle to simplify petty cash management through UPI-based payments. The results include:
500 hours saved monthly across finance and operations
80% drop in duplicate expense submissions
Reimbursement turnaround dropped from 10 to 15 days to 1 to 2 days
₹0 physical cash float inside stores
Store-level caps and amount-based policies to control spending
Approval controls for bills over ₹1,000
Higher visibility and a transparent audit trail throughout the network
Frequently Asked Questions
What is UPI for business?
UPI for business means using UPI-based payment capabilities for legitimate business expenses within an organisation’s defined controls and policies. It refers to applying controls around who can spend, how much they can spend and how transactions are recorded.
Can employees use UPI for business expenses?
Yes. Employees can use UPI for approved business spends where the organisation’s policy, authorisation and configured controls allow it. This includes having the right user permissions, spending limits and monitoring processes set up beforehand.
What is a business QR code payment?
A business QR code payment enables employees to pay a merchant by scanning a QR code. In a business setting, the QR code is the payment interface, while the organisation’s configured controls determine how the payment is governed and recorded.
What controls should finance teams set up for UPI payments?
Finance teams must consider various elements when setting up UPI payments for employees, such as user permissions and approval thresholds, per-user and transaction limits, merchant or category controls and cost-centre attribution and transaction visibility.
How does a company track employees’ UPI expenditure?
Businesses can utilise a centralised spend management platform to get real-time visibility into transactions and track and attribute spends to individuals, groups, categories or departments/locations.
Is it necessary for every UPI payment in a business to be approved?
Not necessarily. Regular payments within given thresholds can follow a simpler workflow or be auto-approved within policy, whereas exceptions and higher-value transactions can be sent for further approval.
Zaggle Admin
Expert contributor and editor at the Zaggle Knowledge Hub, specializing in corporate spend management, expense compliance, and B2B fintech solutions.
In This Article
You May Also Like
How Automated Dashboards Improve Decision-Making for Retail CFOs
Posted on : Aug 18, 2026
How to Spot and Forecast Expense Spikes Early Across Branches
Posted on : Aug 4, 2026
Benefits of Automating Monthly Expense Reconciliation Across Branches
Posted on : Jul 21, 2026