How to Make Every Business QR Code Payment Finance-Ready
A digital payment may be instant. A finance-ready payment needs context. This is the real gap businesses face with a business QR code payment.
The payment may be digital, but the Finance team still needs to know who initiated the payment, what they spent on, which budget it belongs to and whether the supporting documents are available.
Why a Digital Payment Trail Is Not Enough
A QR transaction gives you a record of the payment. It can show details such as the amount, time and merchant. That is useful. But Finance needs more than proof that money moved.
For every business QR code payment, finance teams may also need to establish:
Who made the payment: The transaction should be linked to the authorised employee or spender
What it was for: A merchant name alone does not explain the business purpose
Where it belongs: The expense may need to be assigned to a branch, department, cost centre or project
Which budget it uses: Finance needs to know whether the spend falls within the relevant budget and category
What supports it: A bill, invoice or receipt may still be required
Whether it was approved: Some transactions may need an approval record or policy check
Without this information, the payment is digital, but the accounting process can still remain manual.
Where QR Payment Reconciliation Breaks Down
The biggest reconciliation problems often appear around the payment rather than during it.
Personal UPI Creates a Second Workflow
When employees use personal UPI for business expenses, the transaction is outside the organisation's spending process. The employee pays first. The bill is submitted later. Finance then verifies the expense, processes reimbursement and tries to reconcile the payment with the underlying business expense.
Setting up a controlled UPI for business expenses can keep that transaction within the organisation's payment process from the start.
Generic Transaction Data Does Not Explain Business Purpose
A QR payment can identify a merchant and transaction amount. That does not necessarily tell Finance whether the payment was for maintenance, supplies, local travel or another business expense.
The transaction therefore needs to be connected to the relevant expense category and accounting information.
Delayed Documents Lead to Follow-Ups
The longer employees delay receipts or invoices, the harder it will be to match them to transactions. Finance might end up sending reminders weeks later. This requires manual effort and introduces the risk of incomplete records.
Attribution Gets Lost Across Locations
A business with many branches can make hundreds of small QR payments. Without clear attribution, Finance may know that a payment happened but still have to establish which employee made it, which branch or department incurred it, and which cost centre should be charged.
What a Finance-Ready QR Payment Should Capture
The goal is not simply to create a digital payment record. It is to create a finance-ready payment trail. See the table below for some must-haves for expense management:
Payment information | Why Finance needs it |
Authorised spender | Associates the spend with the employee responsible |
Merchant and amount | Shows where the money went and how much was paid |
Business Purpose | Explains why the payment was made and supports appropriate expense classification |
Expense category | Helps classify the transaction correctly |
Branch or cost centre | Makes sure the expense is allocated to the correct business unit |
Budget information | Helps compare the spend with defined limits or allocations |
Bill, invoice or receipt | Provides supporting documentation for the expense |
Approval or policy record | Indicates if the transaction was conducted in accordance with the necessary controls |
When these details are captured at the time of payment, Finance has less context to reconstruct later and fewer gaps to resolve during reconciliation.
Why Documentation Should Be Captured at the Point of Payment
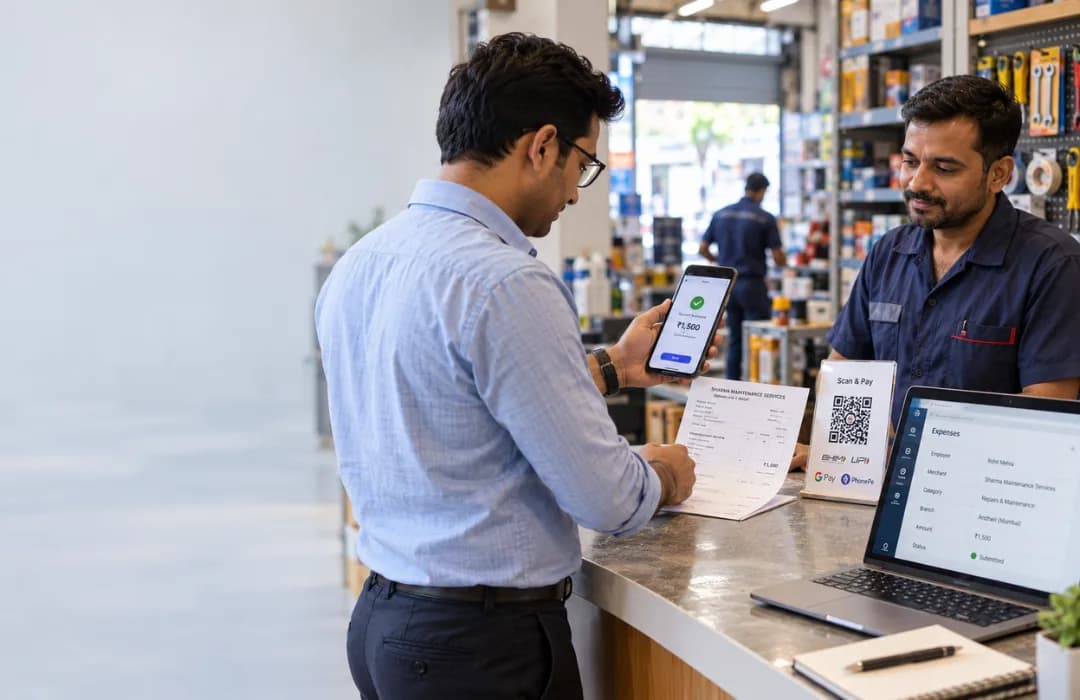
Supporting documentation should be as close to the transaction as possible. Let's take an example of a branch employee who makes a business QR code payment of ₹1,500 to a local maintenance vendor. When the employee uploads the invoice or receipt at the time of payment, finance can view the transaction and supporting documents in one place.
Capturing the document at the point of payment reduces follow-ups, improves the completeness of the expense record and makes the transaction easier to reconcile.
This easier than asking for the same document several weeks later. It can also help improve accounting procedures. Where an invoice contains relevant tax details, capturing that documentation with the transaction can give finance a clearer record for downstream review.
While the payment record does not prove GST eligibility or compliance, it can be used to assist the organisation's accounting and tax procedures if the relevant invoice and tax information is also retained.
How Zaggle Helps Create a Finance-Ready Payment Trail
Zaggle's solution enables businesses to integrate QR-based payments into a controlled expense-management workflow. Business QR code payments can be made by authorised employees using the Zaggle App and not their own UPI accounts. The payment is recorded in the business environment, including transaction information like the amount, time and merchant.
The workflow then connects the payment to the data that Finance needs to reconcile it. Centralised dashboards, expense categories, branch-level visibility and policy controls enable the team to see where the money was spent and how it should be accounted for. It also offers automated reconciliation and digital expense tracking across locations.
Mandatory bill uploads and policy checks can also be included in Zaggle's spend-management solution, enabling businesses to capture supporting documentation closer to the point of spend rather than through repeated follow-ups later.
The result is a more useful payment record. A digital payment trail tells you that a transaction happened. A payment trail that is ready for finance provides you with the information you need to act on it.
Real Impact: How AZA Fashions Digitised Store-Level Expenses
AZA Fashions needed greater control over petty cash across multiple stores. The company chose to implement Zaggle’s solution for branch level spend management via QR. The implementation helped move more than 90% of petty cash transactions to real-time digital tracking. Finance teams also achieved greater category visibility and quicker reconciliation.
The broader rollout resulted in further operational benefits such as a 20% reduction in monthly operating costs, 25% reduction in manpower for petty cash and 30% reduction in cash leakages.
The case study illustrates the main theme of the article: If payment data and supporting information are captured simultaneously, Finance will not have to reconstruct the transaction later.
Frequently Asked Questions
What information does a business QR code payment contain?
QR payment generates a digital transaction record. This can include information like the amount, time and merchant, depending on the payment configuration.
Why is a digital payment trail not enough for reconciliation?
Finance may still require the authorised spender, business purpose, expense category, cost centre, supporting document and relevant approval record.
How does UPI for business minimise reimbursement follow-ups?
A controlled business payment is a legitimate business payment that remains within the organisation's payment workflow. The payment is made by an authorised employee via the organisation's payment system and not via their own UPI and then claiming it back. This eliminates the need to move the transaction to a separate employee reimbursement process.
Why should employees upload bills when they make a payment?
Documentation at the point of payment helps to link the bill or receipt to the payment and minimises the need for follow-up.
Are QR payments suitable for accounting and GST?
They can offer transaction data and, if they support the capture of invoices or bills, Finance can get better documentation for downstream accounting and tax review. However, GST treatment is not dependent on the payment method itself.
What should Finance look for in a QR payment solution?
Look for authorised-user controls, transaction data, expense categorisation, branch or cost-centre attribution, supporting-document capture, approval controls and reconciliation visibility.
Zaggle Admin
Expert contributor and editor at the Zaggle Knowledge Hub, specializing in corporate spend management, expense compliance, and B2B fintech solutions.
In This Article
You May Also Like
Paying Utility Bills Across 40 Locations: Where UPI Fits and Where It Doesn't
Posted on : Oct 28, 2026
How QSR Chains Can Eliminate Cash Leakages with QR-based Payments
Posted on : Oct 26, 2026
Rent, Maintenance and Society Dues: Which Recurring Property Payments Actually Work on UPI?
Posted on : Oct 16, 2026